Diberdayakan oleh Blogger.
Tampilkan postingan dengan label Change. Tampilkan semua postingan

Kamis, 24 April 2014

Change the Direction of Your Fridge Door for Easy Access

Change the Direction of Your Fridge Door for Easy AccessS

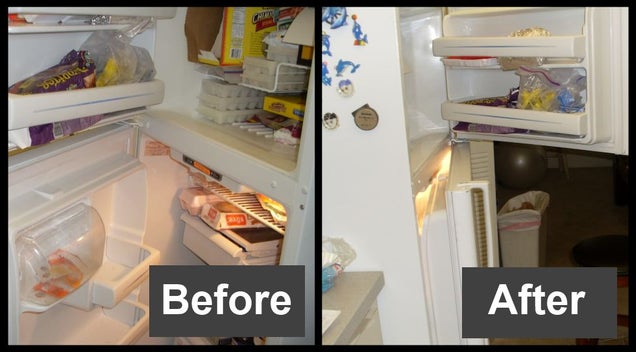
A well-arranged kitchen can make a huge difference in how efficient you are in that space. So if your fridge door often gets in the way, How To Be A Handyman offers a DIY guide to change the direction it opens.

Since your fridge is one of the most accessed parts of your kitchen, it makes sense to streamline its use. You shouldn't be having to work around the fridge's door, it should ideally seamlessly fit into your space, like opening up against a wall.

All you need for this project is a drill and the right screws. It might seem like a small inconvenience to go around a fridge door, but considering this project takes about 10-15 minutes and requires no major changes, it's well worth it. In essence, you will be unscrewing all the hinges of the freezer and main door, and then put the hinges on the other side—your fridge already has a space for them.

The full step-by-step guide at the blog offers all the details and photos you will need.

How To Change The Direction Your Refrigerator Door Swings | How To Be A Handyman via The Kitchn


View the Original article

Senin, 21 April 2014

Dropbox Promises Adding Condoleezza Rice To Its Board Won’t Change Its Privacy Views

After Dropbox announced the hiring of former U.S. Secretary of State and National Security Advisor Condoleezza Rice, the Internet roiled with unrest: Could a former government official who defended warrantless wiretapping during the Bush administration properly advise a cloud storage company at the epicenter of the discussion of data privacy, especially in the current context of the NSA and its surveillance programs?

Many inside the technology community were angered by the choice. Dropbox, a company that was listed as “coming soon” on the first PRISM slides, has joined with other technology companies in calling for reformation of surveillance.

The least we can say is that the announcement of the hire was poorly handled. Dropbox agrees. In a short blog post published today, the company was plain: “We should have been clearer that none of this is going to change with Dr. Rice’s appointment to our Board. Our commitment to your rights and your privacy is at the heart of every decision we make, and this will continue.”

The question is whether the word of the company will suffice to quiet its critics.

Dropbox is currently making a play to shape its products to better serve large corporate clients, a lucrative, large market. Chatter among some users indicates that there is at least mild effort from the plugged-in to leave the service; those leaving individually will likely amount to no more than a day’s rounding error on Dropbox’s growth, however.

But the plugged-in are often the sort that make purchasing decisions regarding the implementation of new technology for large corporations. Could the Rice pickup harm Dropbox there? The company is betting that any potential drag of will be more than made up by their new board member’s deep international experience and intelligence. Regardless of whether you agree with her political philosophy, it’s hard to dispute Rice’s credentials.

But for a company looking to secure revenue ramp and pursue an IPO, running into this level of community unrest must be unwelcome.

Photo: Whitehouse.gov

Minggu, 20 April 2014

This Checklist Reveals the Heartbleed-Affected Passwords to Change Now 2014

This List Reveals the Heartbleed-Affected Passwords to Change Now


This Checklist Reveals the Heartbleed-Affected Passwords to Change Now 2014


By now you've got most likely heard concerning the large Heartbleed safety bug that may have compromised nearly all of the world's web sites. Everybody should change their passwords on the affected sites-however only after these websites have patched the issue.


Mashable is maintaining and updating a list of the most popular sites you should change your passwords for ASAP.


LastPass users have a built-in Heartbleed checker for their accounts, but that doesn't help those of us who don't use LastPass or even new LastPass users. (I imported over 800 accounts into LastPass yesterday and this morning and was told I didn't need to take any action, probably because the tool saw all my passwords as new.)


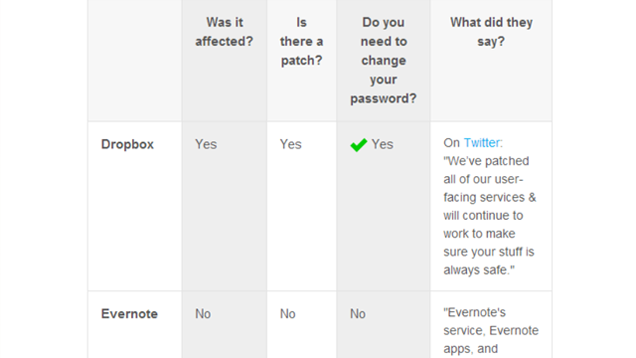
Mashable reached out to the major email, social, finance, and other sites on the web to create this chart showing which sites have been affected, if they've patched it, and if the sites recommend you change your password now.


So you can see at a glance that you should change your Facebook password, but not necessarily your Microsoft one. Google, interestingly, says they patched its services and you don't "need" to change your password, but you probably should (better safe than sorry).


You'll probably want to keep monitoring the Mashable list for those companies (like Apple) who haven't responded yet, and your email inbox for notices from companies that aren't on the list.


Happy change your passwords week.


Update: This list unfortunately doesn't specify if the companies have revoked and reissued their security certificates, which is important for the utmost precaution for them to do before you change your passwords. Most of the companies' statements say they've patched the issue or applied the appropriate fixes, but the certificate status is unclear. So even if the sites are saying everything's fixed, it's better to wait until you know for sure if the certificates have been updated. If you're a LastPass user, they have that data or you can check sites individually at https://lastpass.com/heartbleed/(and it looks like LastPass is starting to roll out info for new users, but it's very incomplete as of this writing). For further reading, see Troy Hunt's post or this one from 1Password.


Posted by: http://gosspot.com/

Writted by: totor


View the Original article

Jumat, 18 April 2014

LastPass Now Tells You Which Heartbleed-Affected Passwords to Change

LastPass Now Tells You Which Heartbleed-Affected Passwords to Change

This week, a giant security hole came to light that affects a large portion of the internet. As different sites recover, you'll need to change your passwords, and now LastPass tells you when to do so.

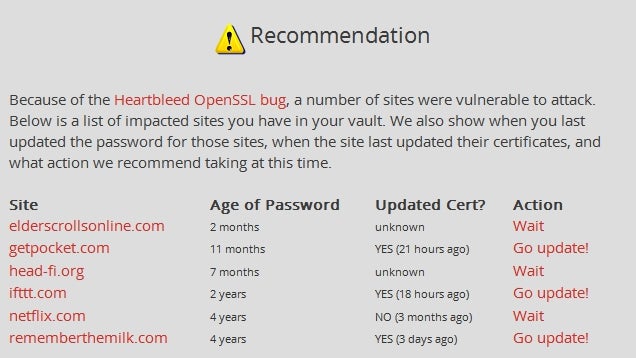
Due to the nature of the Heartbleed bug (read more here), you'll need to wait until affected sites update their infrastructure before you change your passwords. LastPass' ever-useful Security Check tool now includes recommendations for Heartbleed, letting you know which sites have closed the hole, when, and if you should update yet.

To run the tool, just click on the LastPass extension and head to Tools > Security Check. After running the tool, you'll get the results (shown above) so you know what passwords to change. Hit the link to read more.

LastPass Now Checks If Your Sites Are Affected by Heartbleed | LastPass Blog


View the Original article

Senin, 14 April 2014

Enterprises Embrace Inflexibility Instead Of Change

At the AIIM Conference this week in Orlando, it struck me that companies are remarkably inflexible when it comes to adopting new technologies, but the crowd at AIIM wasn’t alone. Perhaps nothing exemplifies this better than the brouhaha over the Windows Start button, a feature which, by the way, dates back to Window 95 — as in 1995.

After 18 years, do you think it’s possible that we could have the imagination to think of a new way of working? Apparently not. Preston Gralla writing on Computerworld was particularly adamant, stating he wanted the Start button back now! You could almost hear him stomping his foot.

But Microsoft customers aren’t just inflexible around a minor change like the Start button; they also have issues with the cloud. Microsoft bought Yammer, a cloud-based enterprise social and collaboration tool, in June, 2012 for a cool $1.2 billion, but many Microsoft customers couldn’t deal with a cloud-based tool of any kind so for about a year, they delivered SharePoint Social on premises and Yammer in the cloud in tandem as part of the latest release of SharePoint. This year they finally put an end to it, and if you’re a SharePoint 2013 customer and you want social, you’ll just have to suck it up and go to the cloud version.

This isn’t just about Microsoft customers, though, because they are far from the only ones. As I moved around AIIM this week, I heard people tip-toeing around the cloud, either deathly afraid of it, or, at most, barely tolerating it. To be fair, these were records managers and this is an area of the enterprise that has been particularly slow to adopt change. But these folks were the living embodiment of cloud FUD.

It wasn’t until the last day when 451 Research analyst Alan Pelz-Sharpe finally gave the audience an opposing viewpoint, telling them, “Don’t tell me the cloud is insecure. You can hire a hacker for $50 to break into your system. They spend hundreds of millions of dollars making their cloud secure.”

I get that change is hard and companies have been burned in the past by chasing the latest computing craze. The data center is littered with bad ERP, CRM and content management installations. But the thing is, this is much more than a craze.

As Dion Hinchcliffe, co-author (with Peter Kim) of Social Business by Design, who followed Pelz-Sharpe as a speaker said, “You can’t chase fashion, but there is no doubt high impact technology is affecting business in so many ways.”

He’s right. This is different because it’s more than the technology flavor of the month. It’s a fundamental change in the way we do business, and companies have to get a grip. Either that or they’ll get left behind by smaller, faster and more agile competitors born in the age of the cloud and mobile who will simply run you over while you’re forming your committee to study the problem.

It’s worth noting that Pelz-Sharpe followed his admonition by saying, “Cloud adoption is a slow burn, not a quick switch.” Indeed, and I don’t hear anyone suggesting you should shutter your private data center and move lock, stock and barrel to the cloud tomorrow. But you have to take the first step at some point, and maybe Microsoft, by forcing its users to adopt Yammer as a cloud-based social tool, is taking the correct approach.

Once they see the sky hasn’t fallen by using the cloud, perhaps companies can begin to test other approaches.

On Twitter today, CITEworld editor Matt Rosoff perhaps put it best when he tweeted: “Execution is hard. You make bets and lose some. Talent recruiting and retention is brutal. Management structure gets ossified.”

But all the more, in the face of these challenges, enterprises cannot afford to sit still and hunker down. They have to start shifting to new ways of working. As Hinchcliffe said, “All of this has significant competitive implications,” and, as such, inflexibility is no longer an option.

Image by Flickr user Jasmine Kaloudis under a CC BY-ND 2.0 license

Minggu, 13 April 2014

Online Banking – 5 Services That Will Change The Way You Bank

It’s not really a stretch to say that the big banks aren’t keeping up with the curve. Not only do they seem perfectly happy to ignore the needs of small customers, but these big banks aren’t really doing well trying to keep up with the mobile-centric lifestyles of today’s urban dwellers. Between the fees and the lack of mobile support from the big banks, it’s no wonder that alternative and mobile-friendly banking solutions are starting to emerge. If mobile payment systems are here to stay, maybe online and mobile-friendly banking is next in line.

Avuba

These mobile banking services take advantage of the possibilities afforded by being online and mobile, providing cool features that you just won’t see in the online apps from your traditional big banks. These services aren’t actually banks themselves, and are still backed by traditional banks, but each provides an interface and features that are worlds apart from what you’d get from a traditional bank’s mobile offerings. Here’s a list of five that might pique your interest.

1. Simple

Simple has been around for a while, and is one of the leading lights in this new generation of online banking services. Simple has easy to use web and mobile banking tools, which come with rich budgeting tools. For instance, you can set goals and request regular reports. You can even deposit checks using your smartphone. Simple is almost entirely free to use; the only fees Simple charges are a $2 International ATM Cash Withdrawal Fee, an $8 Treasurer’s Check Fee and a $1 Over the Counter Cash Withdrawal fee.

Simple

Simple also sends you a Simple Visa card, which can be used like any other card to make purchases. Simple is available by invitation only, and only to residents of the United States. However, Simple was recently acquired by BBVA for $117 million, and although this acquisition doesn’t seem to have changed much yet, there’s a possibility that this acquisition may lead to Simple expanding beyond the United States. The Simple app is available for both Android and iOS.

Simple App

2. GoBank

GoBank is a mobile-first bank that eliminates a lot of the fees and complexity associated with traditional banking. WithGoBank you can sign up straight from your smartphone, and it lets you send money and deposit checks straight from your smartphone. You can also use the GoBank app to create and send a paper check free of charge. GoBank has a large network of free ATMs, with 40,000 free GoBank ATMs spread across the United States. Deposits can be made at any Green Dot retailer, including Wal-Mart.

GoBank

GoBank, like most online banking services, includes robust budgeting tools, such as letting you set custom alerts for specific situations. GoBank gives you your own debit card for free. For added personalization, for a fee of $9, you can even customize it with a photo from Facebook. GoBank is only available for United States residents. Interestingly, GoBank has a negotiable monthly membership fee that ranges from completely free up to $9. GoBank supports both Android and iOS smartphones.

GoBank App

3. Moven

Moven is a mobile banking service and app that has only recently left beta. The app provides a lot of useful real-time information, including real-time updates and spending alerts. Moven also has useful budgeting and bookkeeping features, such as the ability to analyse spending across all your credit and debit cards. Moven even lets you send money through the app using either Facebook, email or mobile phone number. The Facebook integration also lets you see a map of social events, which may come in handy.

Moven

One thing that sets Moven apart, though, is that you can manage other accounts and cards through the app. Moven accounts are almost completely free, with charges only incurred for international ATM withdrawals. You’ll also be charged if you with draw from non-STAR Surcharge-free ATMs, although this is charged by the vendor and not by Moven. Moven is invite-only at the moment, and is only open to residents of the United States. The Moven app is available for Android and iOS.

Moven App

4. Avuba

Avuba is a new mobile-first, completely-digital online bank. Avuba has an always-available 24/7 helpline, and promises that you’ll be able to start banking within 24 hours of signing up. Avuba also supports authentification via text message and all the easy money transfer options you’d expect from a mobile banking app. Avuba offers free credit and debit cards. What’s more, Avuba waives withdrawal fees; even international withdrawals won’t incur any extra fees. Avuba also provides advanced analytics, letting users track their spending behavior thoroughly.

Avuba

Avuba is invite-only at the moment, and is currently entirely free to use, although they are discussing a 7 Euro monthly fee. The site doesn’t seem to explicitly mention any regional limitations, but it’s safe to assume that Avuba is at the very least limited to German residents. Avuba is also one of the 11 startups that’s part of startup accelerator Techstars’ London 2014 intake, which should help raise funds to improve Avuba even further.

Avuba App

5. Holvi

Holvi is an online bank that aims to help businesses, events and associations better manage their finances. Holvi works just like your conventional bank account, but with a clean interface designed for web and mobile use, plus a lot of tools and features that are usually associated with dedicated accounting software and services. For instance, Holvi has real-time invoicing built into the service, alongside budgeting and real-time bookkeeping features. You can also gather expense claims and pay them directly from your account.

Holvi

In addition to these accounting features, Holvi lets you invite other users to manage the same account. Definitely something useful for businesses and associations. This is complemented by an account Feed that lets all users see exactly what’s been going on with the money. Holvi even provides an online store for each account. Holvi is currently only available for Finnish residents, but the company plans to expand its services to the rest of the European Union in the future.

Holvi Interface


View the Original article

Selasa, 25 Maret 2014

Change In UK Tax Law Could Raise The Price Of Music And Apps In The Country

A change in UK tax law that may take force at the start of 2015 would push the price of apps, music and other downloads and “e-services” higher in the United Kingdom.

The legal shift would see downloads in the United Kingdom charged the value added tax (VAT) of that country. Currently, The Guardian reports, companies like Apple and other digital store owners “are allowed to sell digital downloads through countries such as Luxembourg, where the tax rate is as low as 3%.”

International tax law has been good to technology companies, but this particular little riff is coming to the end of its coda.

In practice this should mean that charging a pound for a song is over, and that the cost to consumers for books, apps, and other digital content will rise at once. Naturally, a higher price will limit consumption, and likely induce some to piracy.

Why would the United Kingdon make the change? Simply put, the income. The Guardian also reports that revenue could reach as high as  £300 million for the government. The app economy it appears is large enough that the state wants a piece.

How to tax online purchases is a topic of interest across the pond as well, with the United States currently wrangling with how to levy sales tax on retailers such as Amazon in a uniform, and functional way.

If you live in the UK, keep in mind that this could be your last year at a discount.

IMAGE BY FLICKR USER Kārlis Dambrāns UNDER CC BY 2.0 LICENSE (IMAGE HAS BEEN CROPPED)